Insights

October 2026
Q3 26 insights – Podcast Global Equity Strategy
Dear investors,
Welcome to the Aecus Global Equity Fund’s third quarter commentary for 2026, summarising the period from 30 June 2026 to 30 September 2026. As usual, we share our latest views of the portfolio and the market.
Far from a typical quiet summer lull, the past quarter proved to be a rollercoaster. The AI rally ran out of steam in July. A sharp reversal in market momentum rattled positioning in August. Choppy rotations dominated September as surging oil prices sent shockwaves through the bond market and repeated White House interventions fell short of calming the market.
Against this volatile backdrop, our portfolio companies executed remarkably well, compounding earnings at 8.2% (37% annualised), a record rate for the portfolio. However, share prices lagged as market action remained hyper-concentrated in a narrow group of high-flying AI beneficiaries.
Ultimately, equity investing is a marathon, not a sprint. We remain focused on identifying companies with durable earning power that we believe will lead to sustainable returns. A turbulent quarter does not change our long-term conviction.
Portfolio Fundamentals
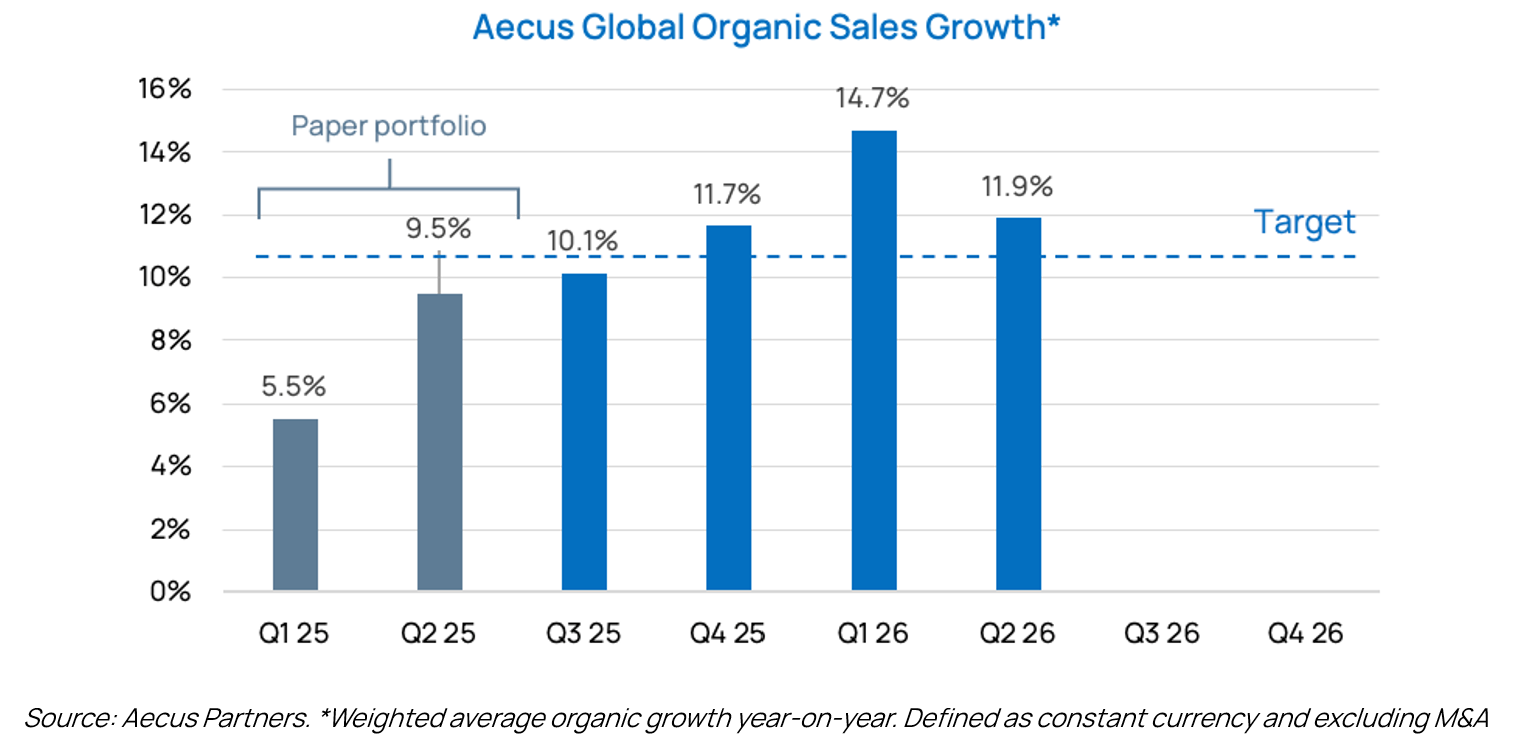
Our portfolio companies delivered 11.9% average organic sales growth, our preferred metric, during the Q2 2026 earnings season. While growth was slightly slower sequentially, this was driven by two stock-specific technical, temporary factors.
First, Nintendo’s revenue mix was heavily skewed toward lower-margin console sales; as the Switch 2 enters the second year of its lifecycle, organic growth rates naturally normalised. Second, Aixtron, a new position added this quarter, posted negative organic growth due to weak prior orders. We anticipate strong double-digit growth going forward.
Even with these headwinds, the portfolio’s aggregate organic growth continues to hold above our target of circa 11%.
Key Highlights:
- Amazon: revenue growth at AWS, Amazon’s cloud computing arm, accelerated to an impressive 37%. Management raised AWS’s long-term revenue target to $1 trillion, a fivefold increase over its current run rate.
- Nintendo: the gaming giant nearly doubled software sales, sending operating profit up 150% year-over-year. Momentum looks strong heading into the holiday season with a Zelda: Ocarina of Time remake due for release in November.
- Waters: just two quarters after closing the largest acquisition in its history, Waters exceeded expectations by turning BD Life Sciences into a mid-single-digit grower. Meanwhile, Waters’ core business was firing on all cylinders, delivering nearly 10% organic growth.
Disappointments:
- Vulcan Materials: the largest aggregates producer in the US missed on both the top and bottom lines, hit hard by severe weather across Texas and the Southeast. Surging diesel costs eroded profits by 6%, a headwind to be recouped by upcoming price increases.
- Tencent: Chinese tech giant Tencent went all-in on its AI investment, pushing free cash flow into the red for the first time in its history. Management is committed to building frontier AI capability at the expense of increased financial leverage. We continue to monitor this carefully.
Portfolio Performance Update
The Fund’s NAV[1] dropped 6.9% (USD) in Q3, driven by a decline in valuations. Underlying portfolio earnings per share grew in the high single digits year-on-year, while valuation multiples compressed in the low double digits over the quarter. Consequently, the Fund’s Next-Twelve-Months (NTM) P/E ratio fell from 25.2x at the end of June to 21.9x by the end of September.
Over 70% of the quarterly decline was concentrated in four AI-related holdings, Disco, KLA, Murata, and Western Digital, which fell by an average of nearly 30%. Crucially, these businesses continue to deliver market-leading earnings revisions (+12% to +30%). Following a crowded Q2 rally, we view this sharp pullback as a healthy correction.
On a positive note, our healthcare holdings extended their Q2 recovery, making meaningful contributions to quarterly performance.
We closed the quarter with 44% exposure to AI infrastructure-related names, 17% to consumer-related businesses, 13% to data businesses, 13% to industrials, and 10% to healthcare.
What have we been thinking about?
Too Much Growth, Not Enough Liquidity
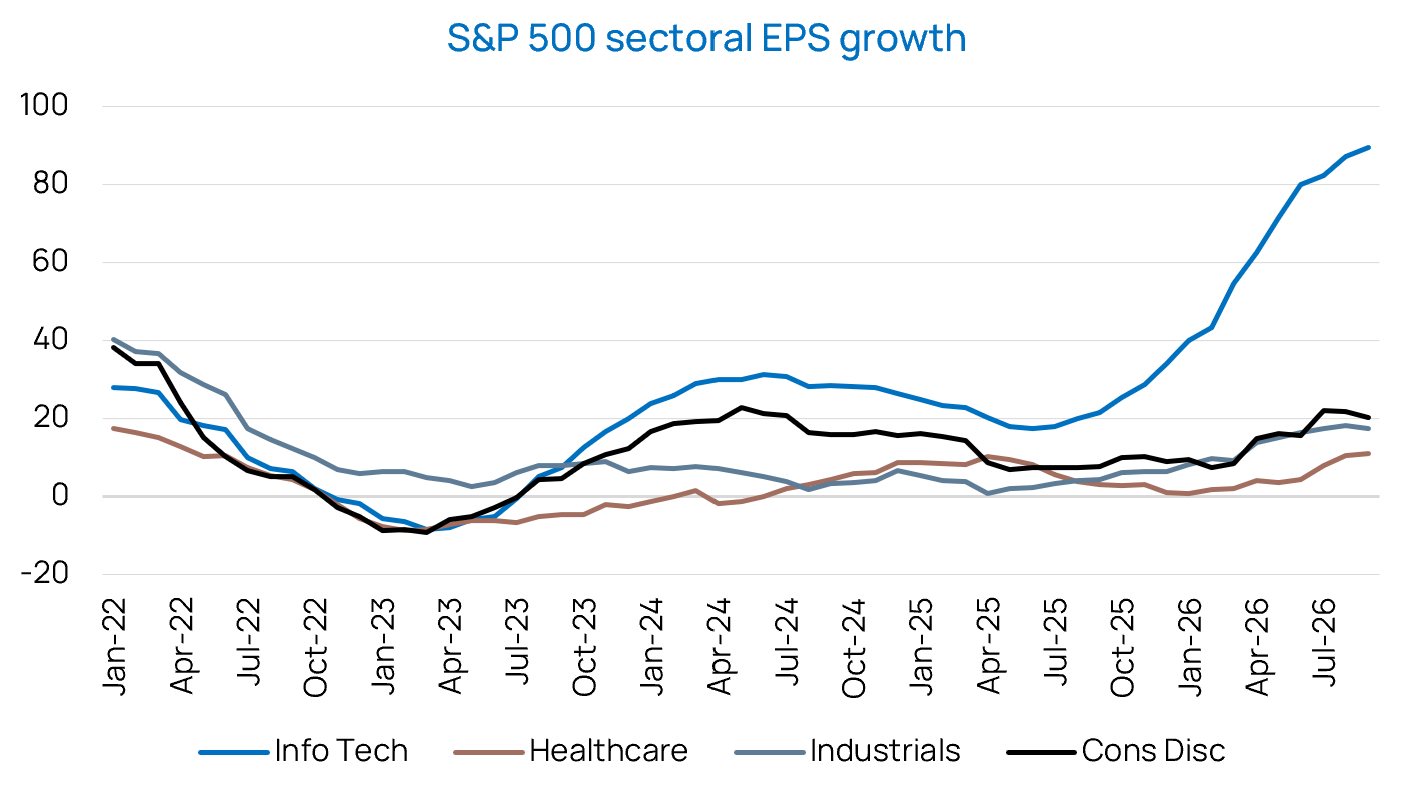
The Q2 2026 earnings season was one of the strongest in decades. EPS across both the MSCI World and S&P 500 indices surged over 37% year-over-year, outpacing even the post-GFC recovery peak. Growth was also remarkably broad-based: every sector outside of consumer staples posted double-digit growth, and all four core sectors targeted by our portfolio (Information Technology, Healthcare, Industrials, and Consumer) saw momentum re-accelerate.
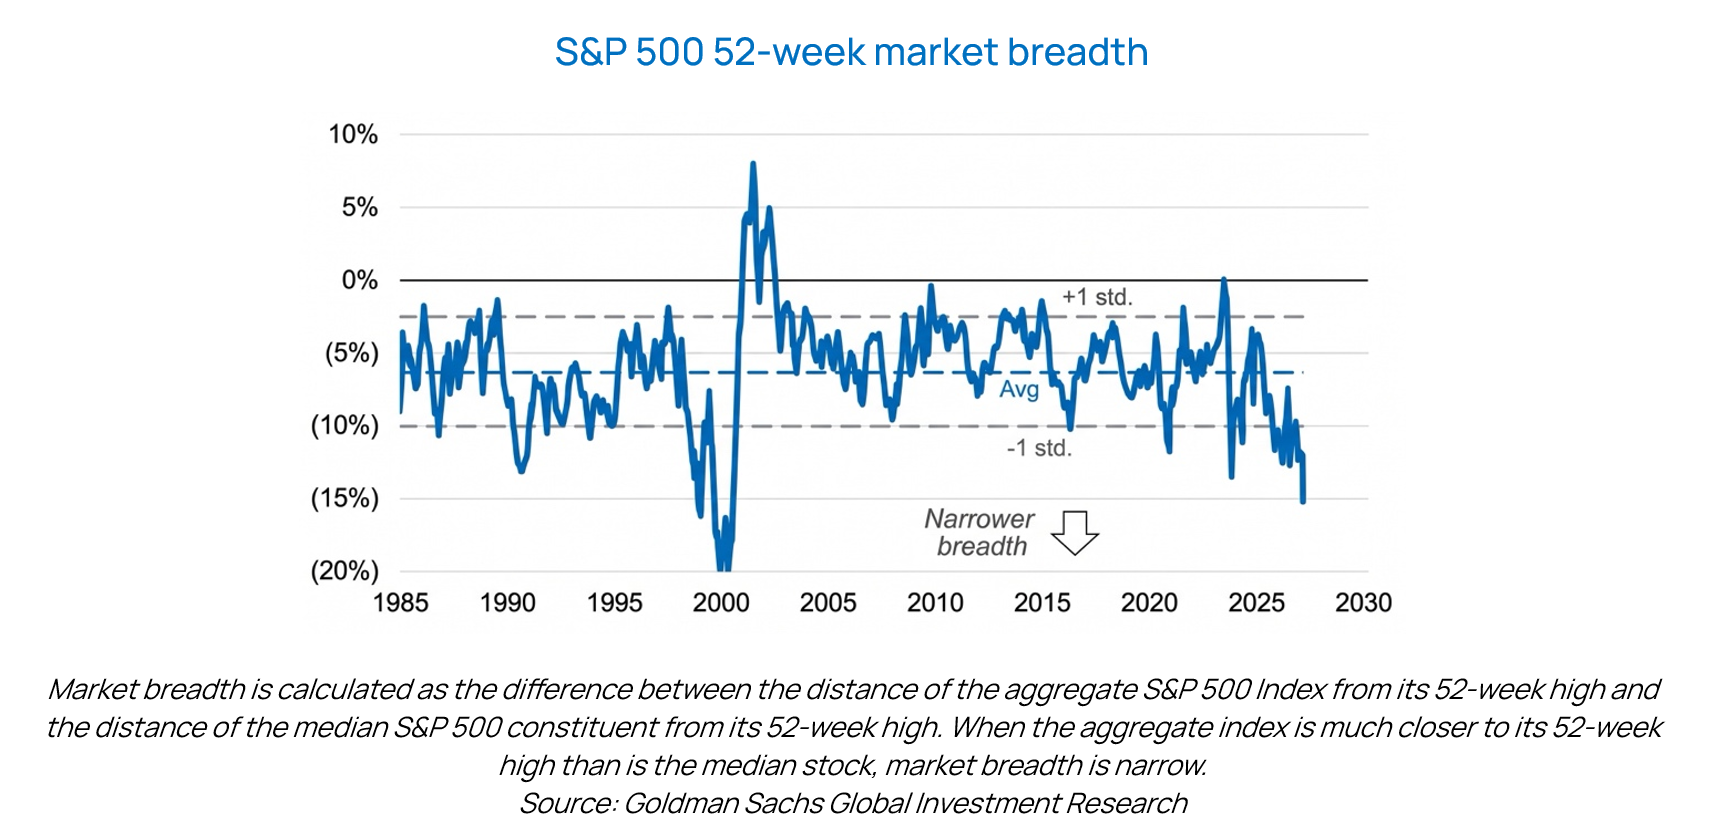
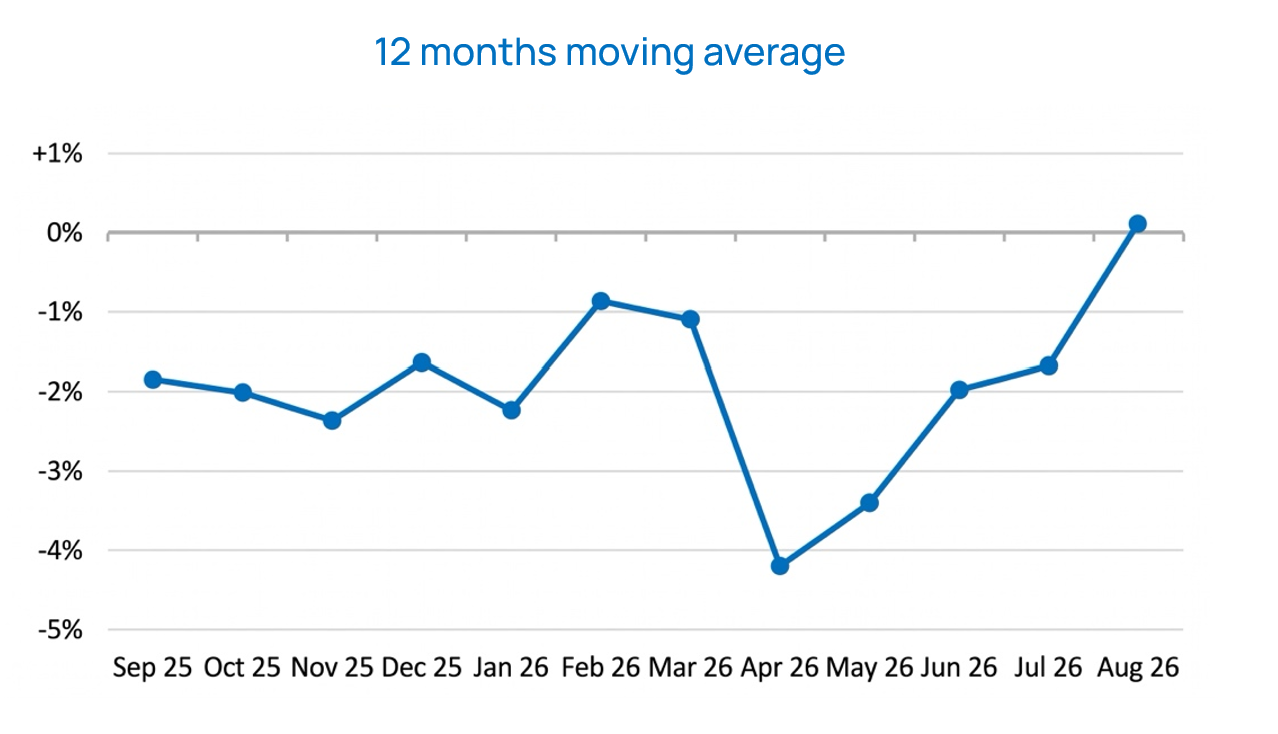
Yet, market breadth dropped to its narrowest level since the dot-com bubble. Even as the MSCI World index hovered near all-time highs, more than half of its underlying constituents were stuck in technical downtrends below their 200-day moving averages, a situation rarely seen outside of major market drawdowns.
We attribute this disconnect to a fundamental dynamic: there is too much growth chasing too little liquidity. With capital tightly constrained, valuation multiples across the broader market are being squeezed lower. The market is rewarding only a narrow set of hyper-growth names with low valuation multiples, such as memory makers who are in the middle of a DRAM supercycle.
While these ultra-growth stories currently hold the spotlight, we believe long-duration assets backed by unique franchises are far better positioned to defend their valuation multiples across all phases of the growth cycle.
Macro from Micro
AI-driven capital expenditure is filtering through global supply chains and catalysing a broad-based industrial recovery. Within our portfolio, Hoya is targeting a 3X output expansion at its Laos HDD plant over the next 12 months. Aixtron saw optoelectronics orders surge more than 8X due to silicon photonics demand from Lumentum, Nokia, and Tower Semiconductor. Cognex issued full-year guidance for the first time ever due to broad end-market strengthening.
Growth momentum is also strong outside of our portfolio. Amongst names that we do not own, Dell, the world’s largest server manufacturer, reported a 10-fold year-on-year surge in AI server orders, leaving backlog nearly doubling quarter-on-quarter. TSMC is contemplating a $300bn investment to double its already massive U.S. manufacturing footprint, pointing to an extended semi capex cycle. Apple, historically secretive about its technology roadmaps, announced plans to enter the AI server market by 2029.
However, as the pace of innovation accelerates, traditional competitive moats are beginning to show signs of erosion. For example, pest control giant Rollins noted demand softness as Google’s AI-generated overviews increasingly favour smaller, localised peers leading to share loss for the market leader.
The consumer segment remained under pressure. Apple’s US iOS revenue declined for the first time in Q2, signalling broader macroeconomic weakness. By contrast, affluent consumers remain resilient. Swiss watch exports returned to growth, driven by double-digit growth at the high end.
Artificial Intelligence
We continue to track AI along three key dimensions outlined in our prior quarterly letter: Technological Progress, Commercial Potential, and Societal Impact. While accelerating model capabilities and expanding market opportunities are compelling, we maintain a prudent perspective regarding the friction and pace of AI adoption across Western institutions and society.
Technological Progress
- Competition among closed-source model developers is intensifying. While Anthropic and OpenAI continue to compete for leadership, Amazon, Tencent, xAI, Google, and Meta are aggressively renewing their efforts to challenge the frontier.
- Model intelligence continues to compound rapidly. AI has made huge breakthroughs across advanced mathematics, theoretical physics, and biochemistry at speeds well exceeding human capacity.
- The surrounding tooling and infrastructure stack continues to evolve, laying the foundation for autonomous AI agents. We see substantial ROI potential if agentic workflows can be integrated into enterprise systems securely and cost-effectively.
- Capital is also available to fund novel approaches, including Fourier Neural Operator (FNO) world models designed to simulate complex physical dynamics.
Commercial Potential
- While hardware and power constraints have driven outsized earnings growth for key suppliers, severe supply chain shortages and rising costs increasingly risk slowing AI deployment and putting hard limits on AI’s growth potential.
- We view Annualised Revenue Run-rate (ARR) across the leading frontier labs as the most reliable indicator of end-user demand. As of September 2026, the combined ARR of OpenAI and Anthropic reached approximately $120 billion. However, sequential revenue growth at Anthropic has stagnated, signalling near-term monetisation friction.
- We estimate that the industry requires $1.5 trillion in high-margin end-user revenue to justify the $1 trillion annual data centre capex. Although AI could unlock multiple high-value end markets such as robotics, AI-native drug discovery and financial services, given the steep revenue ramp needed, we maintain a disciplined and cautiously optimistic approach when managing the Fund’s AI exposures.
Societal Impact
- Political and social dynamics represent our primary area of concern. Repeated cybersecurity incidents are eroding public goodwill, increasing the likelihood of a restrictive regulatory framework that would impair AI’s commercial viability.
- The AI safety debates intensified markedly in Q3. Beyond rhetoric surrounding regulatory capture, leading labs still lack robust safety mechanisms to contain rogue AI agents, an issue reflected in persistent leadership turnover across safety teams at all top labs.
- The incoming assistant attorney-general of the DOJ antitrust division may put Big Tech’s Section 230 immunity under scrutiny, introducing additional liability. With federal policymakers divided between self-regulation and strict oversight, the medium-term regulatory outlook remains highly unpredictable.
- Public opinion regarding data centre build-out has gone from poor to abysmal. Headcount reductions across tech and services firms highlight that AI’s broader economic benefits have yet to diffuse across the labour market.
Outlook
At the end of Q3, the average P/E[1] multiple for the Fund was 21.9x, well below the 10-year average. Based on consensus estimates and Aecus TSR (Total Shareholder Return) model, the portfolio offers an attractive double-digit compounded earnings growth for the next three years.
Given the fast pace of earnings growth and technology development, we continue to seek resilient franchises with defendable business models and growth tailwinds at attractive valuations. We are confident our approach will generate superior long-term returns for our investors.
We thank you again for your interest in the Fund and warmly welcome your questions and comments.
Until next quarter,
Fan, Arnaud & Alistair
[1] Next twelve months Price to Earnings ratio ex cash
Important Information
Issued by Aecus Partners SAS which is regulated by the Autorité des Marchés Financiers (AMF). RCS Paris n° 933 708 976 Agrément AMF n°GP20240027 (https://www.amf-france.org/fr, 17 place de la Bourse – 75002 Paris). The Fund is a sub-fund of the ICAV, an umbrella fund with segregated liability between sub-funds. The Fund is authorised by the Central Bank of Ireland as a UCITS pursuant to the European Communities (Undertakings for Collective Investment in Transferable Securities) Regulations. The ICAV has delegated UCITS management company functions to Aecus Partners SAS as its UCITS management company. The ICAV is authorised by the Central Bank of Ireland pursuant to the Regulations and the Central Bank (Supervision and Enforcement) Act 2013 (Section 48(1)) (Undertakings for Collective Investment in Transferable Securities) Regulations. The distributor of the Fund is Aecus Partners SAS. This financial promotion has been approved by Zeyro (FRN 1001386) on 15 April 2026. This Fund may be suitable for investors seeking long-term capital growth from Global equities, who can commit to a five-year investment horizon and tolerate medium volatility and potential capital loss. It is not suitable for investors requiring capital protection, guaranteed returns, or access to capital within five years.
This document is a communication for information purposes only intended for professional clients. Please refer to the Fund’s prospectus and key information document before making any final investment decision. These documents are available free of charge, in paper or electronic format, from the Fund’s Investment Manager, as well as on the Manager’s website: https://www.aecuspartners.com. This material may not be copied, reproduced, communicated or redistributed, in whole or in part, without prior authorisation from Aecus Partners SAS. Any entity responsible for forwarding this material to other parties takes responsibility for ensuring compliance with applicable financial promotion rules. This material does not constitute a subscription offer and cannot be equated with a recommendation or investment advice. This material is not intended to provide, and should not be relied on for, accounting, legal or tax advice. This material has been provided to you for informational purposes only and may not be relied upon by you in evaluating the merits of investing in any securities or interests referred to herein or for any other purposes. Any specific securities identified and/or described in this document do not represent all of the securities purchased, sold, or recommended for the Fund and no assumptions should be made that the securities identified and discussed were or will be profitable. The information contained in this material may be partial information and may be modified without prior notice. It is not individually tailored for or directed to any particular client or prospective client. Prospective investors should consult their financial adviser before making an investment decision. The sources used to carry out this reporting are considered reliable, however no warranty of accuracy or reliability is given and no responsibility arising in any other way for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Aecus Partners SAS, its officers, employees or agents. Aecus Partners SAS accepts no responsibility for any direct or indirect losses caused by the use of the information provided in this document.
All data is as at the document date unless indicated otherwise. Performance data herein relates to the Aecus Global Equity Fund (the “Fund”). Net asset value performance (NAV) data has been calculated on a NAV-to-NAV basis and is net of management fees and operating expenses, with any income reinvested. A detailed description of the charges that apply is set out in the Prospectus. The ongoing charges figure may change over time. Company holdings and performance are likely to have changed since the report date. Company information, including performance calculations and other data, is provided by Aecus Partners SAS. Past performance may not be a reliable guide to future performance and investors may not get back the amount invested. If an investor’s own currency is different from the currency in which the Fund is denominated, the investment return may increase or decrease as a result of currency fluctuations. All investments involve risk. The value of the investment and the income from it will vary. The figures quoted relate to past periods and past performance is not a reliable indicator of future performance. The Fund uses the MSCI ACWI Net Index (source: MSCI) as a comparator benchmark to compare performance. The Fund is actively managed and is not constrained by any benchmark. Glossary of terms: please refer to the website. Access to funds of an ICAV managed by Aecus Partners SAS may be subject to restrictions regarding certain persons or countries.
EEA – Access to the Fund may be subject to restrictions regarding certain persons or countries. The Fund’s Prospectus and KIDs can be obtained by visiting www.aecuspartners.com/documents and are available in one of the official languages of each of the EU Member States into which the Fund has been notified for marketing under the Directive 2009/65/EC (the UCITS Directive). The Fund is currently notified for marketing into a number of EU Member States under the UCITS Directive.
UK – This Fund is a sub-fund of an Irish UCITS authorised by the Central Bank of Ireland and is not authorised by the UK Financial Conduct Authority (FCA). The Fund is recognised in the United Kingdom under the Overseas Funds Regime (OFR) in respect of certain share classes only. Only those share classes that have been recognised under the OFR may be marketed to investors in the UK. As an overseas fund recognised under the OFR, the Fund is not subject to UK sustainable investment labelling and disclosure requirements. The protections provided by the UK regulatory system, including access to the Financial Services Compensation Scheme (FSCS) and the Financial Ombudsman Service (FOS), do not apply. This document is for information purposes only and does not constitute an offer or solicitation to anyone in any jurisdiction in which such offer or solicitation is not authorised. Cancellation rights do not apply, and U.K. regulatory complaints and compensation arrangements may not apply. This material is issued and approved by Aecus Partners SAS which is authorised and regulated by the Autorité des Marchés Financiers (AMF).
Glossary of terms: please refer to the website
Contacts Aecus Partners: bonjour@aecuspartners.com – +33 (0)1 84 80 81 82 – 128 rue du Faubourg Saint-Honoré – 75008 Paris
[1] Aecus Global Equity Fund A USD ACC share class
Related insights
Insights
This section brings together Aecus Partners’ insights, perspectives and communications. It features a curated selection of content — podcasts, interviews, market updates and commentary — designed to share our views on portfolio companies and investment dynamics. These materials reflect our convictions at a given point in time, with the aim of providing a clear, structured and accessible perspective on complex topics.