Insights

October 2026
Q3 26 insights – Podcast Continental Europe Equity Strategy
Dear investors,
Welcome to the Aecus Continental Europe Equity Fund’s third quarter commentary for 2026, summarising the period from 30 June 2026 to 30 September 2026.
During the period, European equity markets ebbed and flowed with political and business narratives. Sharp sector rotations were driven by evolving US–Iran negotiations and by AI-related news swinging investor sentiment between optimism and caution. All this noise distracted from one of the strongest European first-half corporate reporting seasons of the decade. High energy prices and elevated long-term interest rates gave a strong lift to earnings in energy, utilities and banking, while strong data center demand drove semiconductor profits.
Since the beginning of the year, analysts’ consensus expectations for 2026 earnings per share for the MSCI Europe ex-UK Index have been revised upward by 5%. Despite an uncertain political backdrop, persistent inflation and tight monetary conditions, companies in the Index appear poised to deliver high-single-digit organic sales growth and mid-teens earnings growth. These levels are more characteristic of a post-recession reacceleration than of the current unremarkable macro environment. This unusual strength at the micro level also underscores the rare disconnect that has emerged between bond and equity markets over the past three months.
Portfolio Fundamentals
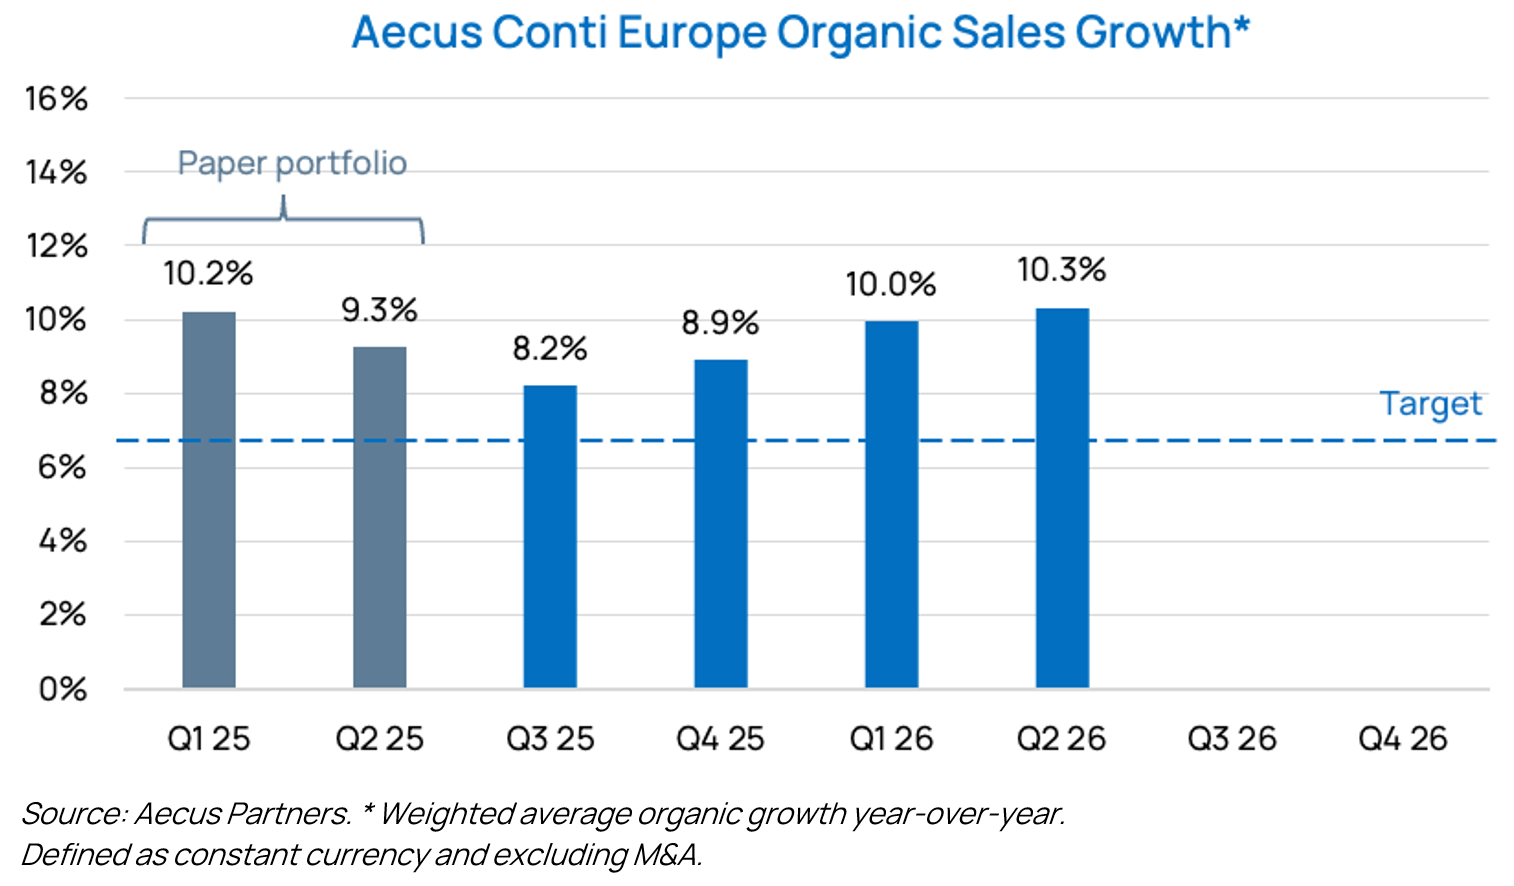
Overall, our Fund’s companies delivered outstanding operating performance during the second quarter. The portfolio’s aggregate organic sales growth remained above 10% for the second consecutive quarter and was broad-based:
- Companies exposed to the construction sector have turned the corner (Kingspan, Sika);
- Galderma showed exceptional strength in dermatological skincare and aesthetic injectables sales, while the rapid penetration of its new blockbuster treatment for atopic dermatitis supported very positive operating leverage;
- ASML’s earnings and guidance triggered a 60% upgrade to 2027 earnings expectations, reflecting improved EUV and DUV production capacity and a higher gross margin;
- Our data-related companies, RELX and Experian, once again delivered steady and solid organic revenue growth (+7%), defying the more apocalyptic predictions surrounding AI;
- Novonesis, the world leader in biosolutions, raised its 2026 organic growth guidance from 5-7% to 7-8%, as sales synergies and more recent commercial investments in emerging markets continue to pay off handsomely.
Setbacks were relatively limited during the quarter:
- bioMérieux reduced guidance as budgetary constraints among US hospitals began to translate into pricing pressure and lower volumes. Although we believe the company remains capable of delivering revenue growth at the upper end of its medium-term 3-6% guidance range, this is still around 2% below our previous expectations;
- Coloplast’s 6% organic growth remained below medium-term targets. While its core chronic-care franchise remains dynamic overall, performance was held back by the recently acquired Kerecis biologics business and more challenging conditions for ostomy care in China.
Beyond organic growth, one metric we track closely as a “portfolio sanity check” is the evolution of consensus earnings estimates to gauge whether our companies are generally beating estimates, or disappointing. Year to date, the portfolio’s aggregate consensus estimates for 2027 earnings per share have been revised upward by 4%, with very few companies suffering EPS downgrades. This is certainly encouraging and consistent with the broader European stock market, where earnings expectations have been notably boosted by the exceptional strength of energy prices and interest rates. Importantly, the portfolio’s earnings progression is underpinned by high-quality business value creation rather than short-term macroeconomic conditions, which we believe will prove to be more durable over time.
Portfolio Performance Update
The Fund’s NAV[1] was broadly flat for the quarter (-0.05% EUR), impacted mostly by the month of September when the end of the US-Iran ceasefire, elevated energy prices and rising bond yields all weighed on company valuations. We view these as short term market factors and remain focused on the strong underlying fundamentals and value creation of our companies.
We were particularly pleased by the rebound in the construction names we had held in the portfolio through an otherwise difficult environment. Kingspan stands out: the growth story is now both broadening and accelerating. Advnsys, its data-infrastructure division, is riding the explosive build-out of AI data centers with order intake for its data-specific cooling and containment solutions increasing fourfold during the quarter while the core Insulated Panels business is also re-accelerating, with order intake up 13%. With organic revenue growth already at +12% in H1 and the US roofing business moving into commercial production soon, we believe that Kingspan is likely to be firing on all cylinders through the end of the decade.
Coloplast shares recovered as fundamentals showed signs of stabilising and early comments from the newly appointed CEO proved encouraging.
As doubts emerged over the pace of AI development, companies exposed to the data center buildout came under pressure (ASML, Aixtron, Besi). Conversely, several companies previously seen as potential “AI losers”, notably in data and software, staged a rebound. Dassault Systèmes and RELX were among them.
Lindt shares fell after the company lowered its full-year 2026 organic sales growth guidance from 4–6% to 0–2%, reflecting a longer-than-expected shift from price-led to volume-led growth. By reinvesting the benefit of lower cocoa prices into marketing and promotional activity, the company should support volumes going forward. In our view, the current depressed valuation more than prices in the uncertainty around how long this delicate transition will take.
What have we been thinking about?
Something has got to give
The prolonged divergence between bond and equity markets is a cause for concern. We have seen it several times before, and it has rarely persisted for long. How it ends depends on what is driving it. This gap can close in a benign way when yields are simply reverting to their mean and growth is normalising, as in 2013, 2017 and 2022. But it can also lead to a sharp equity correction when rising rates reflect more persistent policy tightening or inflation, when earnings are flattered by temporary or artificial factors, and when valuations sit well above their historical average, as in the late 1990s and in 2005–2007. For the moment, it remains quite an early phenomenon that is easily explainable through excellent corporate results and the expected temporary nature of the Iran – US conflict. Valuations are also more moderate than in previous sharp corrections. Several supporting factors like rising oil prices and high interest rates might be short-lived.
The AI gold rush
The artificial intelligence boom and the torrent of capital expenditure this gold rush requires has driven a sharp acceleration in the earnings of its beneficiaries. The momentum has become such a powerful short-term magnet that many investors seem to have forgotten a basic truth: even a supercycle has a peak, and a peak implies a trough. With no one quite sure how long this cycle will run, these assets have grown extraordinarily volatile, lurching from euphoria to despair with every scrap of sector news. Over the past two months, fears have weighed on sentiment about the still-modest returns being generated on AI-lab investment, followed by fears of a slowdown to ensure model safety or as a result of heavy-handed regulation. Barely six months ago, in spring, investors were elbowing each other aside to buy into a sector that promised limitless capital spending. There is a silver lining: now that fear has succeeded greed, the pricing of AI-related assets rests on firmer ground, with investors insisting on proof of improving returns and a clearer view of the demand road map before paying up.
The main constraints on the AI roadmap have shifted from GPUs to physical infrastructure. Chip supply remains tight, but the real bottleneck is now the ability to build, power and bring data centers online quickly. Access to electricity and the speed of capacity deployment are holding back hyperscaler expansion. Instead of a strong and short-lived cycle, data center deployment is very likely to be slower but more prolonged.
Outlook
Each earnings season gives us a quarterly quality check on the portfolio, which we complement with deeper research throughout the year. This may include meeting with a range of company representatives, conducting on-the-ground investigation across a company’s ecosystem and holding expert calls. Our main goal is to verify whether the sustainable portfolio value creation engine identified within our business case remains intact. In our view, the fundamentals remain strong. For several quarters now, the portfolio’s aggregate organic sales growth has reached above 10%, above our long-term target of high single digit. With the drag from adverse currency moves and US tariffs now fading, this growth is increasingly feeding through to strong double-digit earnings-per-share growth.
So far, this real business momentum has not been reflected in share-price performance, as valuation multiples have remained under pressure. A higher-for-longer rate environment is often seen as a headwind for long-duration franchise valuations. Yet it is precisely in such an environment that their fundamental strengths matter most. Our holdings carry little debt and most fund their growth from internally generated cash flows. Higher financing costs therefore have limited impact on their earnings. Strong pricing power and high returns on capital also allow our companies to pass on inflation and keep reinvesting through the cycle, often gaining market share when weaker players retrench.
Decades of investing in secular growth leaders have taught us that, over the long run, steady earnings growth works like a coiled spring. It compresses when multiples de-rate and releases when they revert to the mean. Price-to-earnings ratios can reach extreme lows, but they tend to revert to the mean unless a company’s competitive advantage or growth potential has been permanently impaired. In financial markets, mean reversion can be a powerful and reliable force. Today’s higher rates have compressed the spring through valuations, not through fundamentals.
That is where we are today. The AI debate has become so loud that many sectors with solid secular growth, which simply lack AI’s momentum, have quietly become bargains, in our view. At the same time, the appeal of energy and banks has drawn money into cyclical stocks and out of more defensive names. We remain focused on highly visible and diversified drivers of long-term growth. Momentum can dominate the weighing machine for a while; over time, compounding carries the vote.
We thank you again for your interest in the Fund and warmly welcome your questions and comments.
Until next quarter,
Alistair, Arnaud & Sébastien
[1] Aecus Continental Europe Equity Fund A EUR ACC share class
Important Information
Issued by Aecus Partners SAS which is regulated by the Autorité des Marchés Financiers (AMF). RCS Paris n° 933 708 976 Agrément AMF n°GP20240027 (https://www.amf-france.org/fr, 17 place de la Bourse – 75002 Paris). The Fund is a sub-fund of the ICAV, an umbrella fund with segregated liability between sub-funds. The Fund is authorised by the Central Bank of Ireland as a UCITS pursuant to the European Communities (Undertakings for Collective Investment in Transferable Securities) Regulations. The ICAV has delegated UCITS management company functions to Aecus Partners SAS as its UCITS management company. The ICAV is authorised by the Central Bank of Ireland pursuant to the Regulations and the Central Bank (Supervision and Enforcement) Act 2013 (Section 48(1)) (Undertakings for Collective Investment in Transferable Securities) Regulations. The distributor of the Fund is Aecus Partners SAS. This financial promotion has been approved by Zeyro (FRN 1001386) on 15 April 2026. This Fund may be suitable for investors seeking long-term capital growth from European equities, who can commit to a five-year investment horizon and tolerate medium volatility and potential capital loss. It is not suitable for investors requiring capital protection, guaranteed returns, or access to capital within five years.
This document is a communication for information purposes only intended for professional clients. Please refer to the Fund’s prospectus and key information document before making any final investment decision. These documents are available free of charge, in paper or electronic format, from the Fund’s Investment Manager, as well as on the Manager’s website: https://www.aecuspartners.com. This material may not be copied, reproduced, communicated or redistributed, in whole or in part, without prior authorisation from Aecus Partners SAS. Any entity responsible for forwarding this material to other parties takes responsibility for ensuring compliance with applicable financial promotion rules. This material does not constitute a subscription offer and cannot be equated with a recommendation or investment advice. This material is not intended to provide, and should not be relied on for, accounting, legal or tax advice. This material has been provided to you for informational purposes only and may not be relied upon by you in evaluating the merits of investing in any securities or interests referred to herein or for any other purposes. Any specific securities identified and/or described in this document do not represent all of the securities purchased, sold, or recommended for the Fund and no assumptions should be made that the securities identified and discussed were or will be profitable. The information contained in this material may be partial information and may be modified without prior notice. It is not individually tailored for or directed to any particular client or prospective client. Prospective investors should consult their financial adviser before making an investment decision. The sources used to carry out this reporting are considered reliable, however no warranty of accuracy or reliability is given and no responsibility arising in any other way for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Aecus Partners SAS, its officers, employees or agents. Aecus Partners SAS accepts no responsibility for any direct or indirect losses caused by the use of the information provided in this document.
All data is as at the document date unless indicated otherwise. Performance data herein relates to the Aecus Continental Europe Equity Fund (the “Fund”). Net asset value performance (NAV) data has been calculated on a NAV-to-NAV basis and is net of management fees and operating expenses, with any income reinvested. A detailed description of the charges that apply is set out in the Prospectus. The ongoing charges figure may change over time. Company holdings and performance are likely to have changed since the report date. Company information, including performance calculations and other data, is provided by Aecus Partners SAS. Past performance may not be a reliable guide to future performance and investors may not get back the amount invested. If an investor’s own currency is different from the currency in which the Fund is denominated, the investment return may increase or decrease as a result of currency fluctuations. All investments involve risk. The value of the investment and the income from it will vary. The figures quoted relate to past periods and past performance is not a reliable indicator of future performance. The Fund uses the MSCI Europe ex UK Net Index (source: MSCI) as a comparator benchmark to compare performance. The Fund is actively managed and is not constrained by any benchmark. Glossary of terms: please refer to the website. Access to funds of an ICAV managed by Aecus Partners SAS may be subject to restrictions regarding certain persons or countries.
EEA – Access to the Fund may be subject to restrictions regarding certain persons or countries. The Fund’s Prospectus and KIDs can be obtained by visiting www.aecuspartners.com/documents and are available in one of the official languages of each of the EU Member States into which the Fund has been notified for marketing under the Directive 2009/65/EC (the UCITS Directive). The Fund is currently notified for marketing into a number of EU Member States under the UCITS Directive.
UK – This Fund is a sub-fund of an Irish UCITS authorised by the Central Bank of Ireland and is not authorised by the UK Financial Conduct Authority (FCA). The Fund is recognised in the United Kingdom under the Overseas Funds Regime (OFR) in respect of certain share classes only. Only those share classes that have been recognised under the OFR may be marketed to investors in the UK. As an overseas fund recognised under the OFR, the Fund is not subject to UK sustainable investment labelling and disclosure requirements. The protections provided by the UK regulatory system, including access to the Financial Services Compensation Scheme (FSCS) and the Financial Ombudsman Service (FOS), do not apply. This document is for information purposes only and does not constitute an offer or solicitation to anyone in any jurisdiction in which such offer or solicitation is not authorised. Cancellation rights do not apply, and U.K. regulatory complaints and compensation arrangements may not apply. This material is issued and approved by Aecus Partners SAS which is authorised and regulated by the Autorité des Marchés Financiers (AMF).
Glossary of terms: please refer to the website
Contacts Aecus Partners: bonjour@aecuspartners.com – +33 (0)1 84 80 81 82 – 128 rue du Faubourg Saint-Honoré – 75008 Paris
Related insights
Insights
This section brings together Aecus Partners’ insights, perspectives and communications. It features a curated selection of content — podcasts, interviews, market updates and commentary — designed to share our views on portfolio companies and investment dynamics. These materials reflect our convictions at a given point in time, with the aim of providing a clear, structured and accessible perspective on complex topics.